You can earn a good salary and still struggle with money.
You can also earn a modest income and gradually build a strong financial foundation. The difference often isn’t one brilliant investment or a secret money strategy. It’s the collection of decisions you make repeatedly over many years.
Unfortunately, financial mistakes have a way of hiding in everyday life. A monthly payment seems affordable. A credit card balance doesn’t seem urgent. Retirement feels decades away. An insurance policy gets renewed without being reviewed. Before long, several seemingly small decisions can become expensive problems.
Financial education can help you recognize those problems earlier.
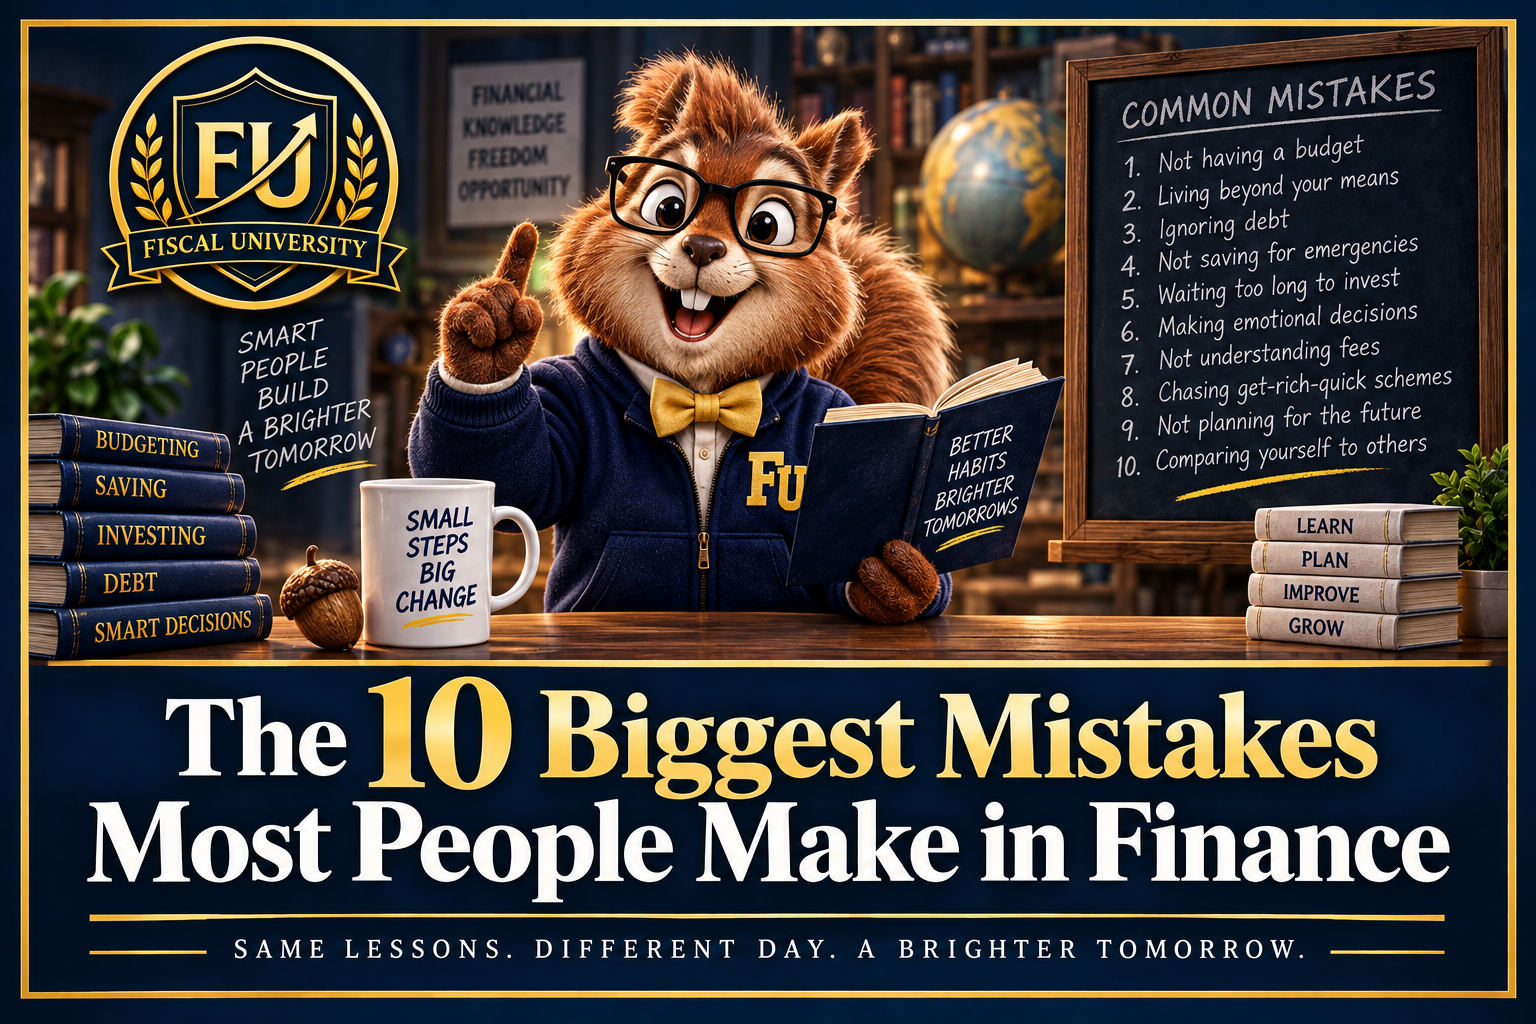
Here are 10 common financial mistakes to watch for, questions worth asking yourself, and situations where speaking with a qualified professional may make sense.
1. Spending Without Looking at the Bigger Picture
Knowing you have enough money in your checking account today isn’t the same as knowing you can afford your lifestyle.
One of the easiest financial traps is managing money purchase by purchase instead of month by month.
Start looking at the complete picture. Add up housing, transportation, groceries, utilities, subscriptions, insurance, entertainment, debt payments, and other regular expenses. Then compare the total with the money actually reaching your bank account.
Ask yourself one simple question:
If my current spending continued for the next 12 months, would I be happy with where my finances ended up?
If the answer is no, something needs to change.
A budget doesn’t have to restrict every purchase. Its purpose is to give your money direction.
2. Treating Available Credit Like Available Money
A $10,000 credit limit does not mean you have an extra $10,000.
Credit cards make it possible to spend tomorrow’s income today. Used carefully, they can be convenient financial tools. Used without a repayment strategy, they can create balances that become increasingly difficult to eliminate.
Interest is especially important to understand. Carrying a balance can cause yesterday’s purchases to continue costing money long after you’ve used whatever you bought.
Before charging something you can’t immediately pay off, ask:
What will this purchase actually cost me if I carry the balance?
If you’re already struggling with credit card payments, don’t simply ignore the bills. Contacting the card issuer early may reveal available options, and a reputable nonprofit credit counselor may be another resource.
3. Having No Financial Backup Plan
Life doesn’t schedule emergencies around payday.
Cars need repairs. Appliances stop working. People lose jobs. Homes require maintenance. Medical bills appear unexpectedly.
When there’s no money reserved for surprises, an unexpected expense can become a credit card balance or loan.
That’s why having accessible emergency savings can be so useful. Even a relatively small reserve can provide another option when something goes wrong.
Instead of becoming overwhelmed by a huge savings target, start with a number you can realistically pursue.
Then keep building.
Your emergency fund isn’t supposed to impress anyone. It’s supposed to be there when you need it.
4. Choosing a Loan Based Only on the Monthly Payment
“$499 a month” sounds much easier to evaluate than a complicated loan agreement.
That’s exactly why consumers should look beyond the payment.
A longer loan term can sometimes make an expensive purchase appear more affordable because the cost is stretched over additional months or years.
Before borrowing money, find out:
- What is the interest rate?
- Is the rate fixed or variable?
- How long will I be making payments?
- Are there additional fees?
- Is there a prepayment penalty?
- How much will I repay in total?
Whether you’re financing a vehicle, consolidating debt, or taking another type of loan, the monthly bill tells only part of the story.
5. Putting Retirement Off Until “Later”
There will almost always be something competing with retirement for your money.
At 25, retirement can seem irrelevant. At 35, you might have a mortgage and children. At 45, other financial responsibilities haven’t magically disappeared.
That’s why continually waiting for the perfect time can become a problem.
If your employer offers a retirement plan, learn how it works rather than automatically ignoring it. Find out whether your employer contributes, what investment choices are available, and what fees may apply.
Retirement planning becomes particularly important as you approach the end of your career. A qualified financial planner or retirement professional may help you evaluate issues such as savings goals, investment risk, retirement income, and withdrawal strategies.
The question shouldn’t only be, “Can I afford to save for retirement?”
Also ask, “What happens if I never start?”
6. Increasing Your Lifestyle Every Time Your Income Increases
Making more money should improve your financial situation.
But that doesn’t always happen.
Imagine receiving a $500 monthly increase in take-home pay and immediately adding a $450 monthly expense. Your income increased significantly, yet your financial flexibility barely changed.
This doesn’t mean you can’t enjoy a raise.
Instead, decide what you’ll do with additional income before it quietly becomes additional spending.
You might use part of a raise to improve your lifestyle while directing another portion toward debt, savings, retirement, investments, or another goal.
Making more money creates opportunity. What you do with the increase determines how much of that opportunity you keep.
7. Buying Investments Because Other People Are Excited About Them
Financial excitement can be dangerous.
When an investment is rising quickly and everyone seems to be talking about it, the fear of missing out can make research feel unnecessary.
That’s backwards.
Excitement should create more questions, not fewer.
Before investing, ask:
What exactly am I buying?
How is this investment supposed to generate a return?
How much could I realistically lose?
What fees or expenses are involved?
How does this fit with the rest of my investments?
If you’re considering a substantial investment and aren’t confident evaluating it yourself, an appropriately licensed investment professional or financial adviser may be able to provide guidance.
Never let someone else’s enthusiasm replace your own research.
8. Paying for Insurance Without Understanding Your Coverage
Many people think about insurance when they purchase the policy and then barely think about it again.
Years later, their circumstances may be completely different.
Insurance is designed to transfer certain financial risks, but policies have limits, exclusions, deductibles, and conditions. Simply having a policy doesn’t necessarily mean you’re protected against every possible loss.
Periodically review your coverage.
Depending on your circumstances, that could include auto, homeowners, renters, health, disability, life, or other insurance.
An insurance agent, broker, or other qualified insurance professional can explain available coverage. Ask what is covered, what isn’t covered, what your limits are, and how much you would personally be responsible for after a loss.
The worst time to discover a coverage gap is after something has already happened.
9. Making a Big Financial Move Without Checking the Tax Consequences
Taxes can turn an apparently simple financial decision into a complicated one.
Selling an investment, withdrawing retirement money, starting a business, selling property, receiving certain types of income, or making other significant financial moves can potentially create tax considerations.
That’s why tax planning shouldn’t always begin when it’s time to file a return.
For decisions involving meaningful amounts of money, it may be useful to speak with a CPA, enrolled agent, tax attorney, or other appropriately qualified tax professional beforehand.
Ask:
Could this decision create a tax bill?
Are there reporting requirements?
Would changing the timing affect the outcome?
Getting an answer before acting may be much more useful than discovering an unexpected consequence afterward.
10. Waiting Until There’s a Crisis to Ask for Help
Professional guidance isn’t reserved for wealthy people.
It also shouldn’t necessarily be reserved for emergencies.
Different financial situations call for different types of expertise.
For tax questions, you may need a CPA, enrolled agent, or tax attorney. For investing or long-term planning, you might consult an appropriately qualified financial planner or investment professional. Insurance questions may belong with a licensed insurance professional. Estate-planning matters may require an attorney. Mortgage questions may be appropriate for a mortgage broker or loan professional. Serious debt problems may warrant speaking with a reputable nonprofit credit counselor.
The best time to seek professional assistance is often before signing paperwork, transferring large amounts of money, making an irreversible decision, or allowing a manageable problem to become an emergency.
And remember: hiring a professional doesn’t mean surrendering responsibility for your finances.
Ask about qualifications.
Ask how they’re paid.
Ask about fees.
Ask about alternatives.
Ask them to explain anything you don’t understand.
You should know what you’re agreeing to before you agree to it.
Better Finances Often Begin With Better Questions
Personal finance can become incredibly complicated, but many of its most important lessons are surprisingly basic.
Know what you spend.
Respect the cost of debt.
Prepare for unexpected expenses.
Look beyond monthly payments.
Give retirement serious attention.
Don’t automatically spend every raise.
Research investments before risking your money.
Understand your insurance.
Think about taxes before making major moves.
And recognize when a situation deserves professional guidance.
You don’t need to master the entire financial system to start improving your finances.
You simply need to keep learning.
At Fiscal University, that’s the point: making financial information easier to understand and available to anyone who wants to learn—without trying to sell you a financial product.
Disclaimer
Fiscal University provides free financial education and general information. Fiscal University is not a financial expert, financial adviser, investment adviser, broker, accountant, CPA, tax professional, attorney, insurance professional, or lender. Nothing in this article should be interpreted as personalized financial, investment, tax, legal, credit, or insurance advice.
We do not sell or recommend financial products through this article. The information is provided freely for educational purposes.
Financial circumstances vary from person to person, and financial rules, laws, taxes, products, interest rates, and other conditions can change. Always do your own research, verify information independently, and consider consulting an appropriately qualified professional before making important financial decisions.