Real estate has a way of making people believe that whatever is happening today will continue forever.
When home prices are climbing, people worry they’ll never be able to afford a house if they don’t buy immediately. When mortgage rates rise, buyers may decide they’ll wait until rates come back down. When homes take longer to sell, homeowners can start wondering whether they missed their opportunity. Renters may watch all of it and decide that staying on the sidelines is the safest option.
But real estate markets change.
Interest rates change. Inventory changes. Buyer demand changes. Local economies change. Construction changes. And people’s personal circumstances certainly change.
That’s why anyone considering buying, selling, or renting should understand one of the most valuable lessons history can offer:
Learn from the past—but don’t assume it’s the future.
Real Estate History Is a Teacher, Not a Crystal Ball
Looking backward can provide valuable context for what’s happening today.
The problem comes when people assume that similar circumstances must produce identical outcomes.
The 2008 housing crash is probably the clearest example. Whenever housing becomes expensive or the market begins slowing, comparisons with 2008 inevitably appear.
But simply saying, “Home prices are high, so another 2008 is coming,” ignores what actually contributed to that crisis.
The housing collapse involved a complicated combination of factors, including risky mortgage lending, highly leveraged borrowers, falling home values, foreclosures, financial-market problems and excess housing supply in many areas.
That doesn’t mean another housing downturn could never happen.
It means the next downturn doesn’t have to look like the last one.
The same principle applies when looking at periods of high mortgage rates, rapidly increasing home values or housing shortages.
History gives us examples to study. It doesn’t give us tomorrow’s headlines.
Stop Thinking About “The Housing Market”
Here’s something that gets lost in national real estate conversations:
There isn’t just one housing market.
A television report might say home sales are slowing nationally while homes in a particular neighborhood continue receiving multiple offers. Condo inventory could be increasing while nearby single-family homes remain difficult to find.
Even within one city, a $250,000 condo and an $800,000 single-family home can exist in very different markets.
That’s why broad headlines should be the beginning of your research—not the end of it.
If you’re thinking about making a real estate decision, narrow your focus.
Look at the city. Then the neighborhood. Then the property type. Then your price range.
Ask questions such as:
How long are comparable properties staying on the market? Are sellers reducing prices? How much inventory is available? Are properties selling above or below their asking prices? What are comparable homes actually selling for?
The closer you get to the market you’re actually considering, the more useful the information becomes.
Buyers Need to Know Their Goal
One of the biggest mistakes a prospective buyer can make is asking:
“Is now a good time to buy?”
There’s no universal answer because buyers don’t all have the same objective.
Someone purchasing a home they intend to live in for 15 years may evaluate today’s market very differently from someone hoping to renovate and resell a property within 12 months.
Your finances matter too.
What can you comfortably afford each month?
How much money would remain after your down payment and closing costs?
Would you still have emergency savings?
How would taxes, insurance, association fees, maintenance and repairs affect the real monthly cost?
Mortgage rates certainly matter, but they’re only one piece of a much larger financial decision.
Instead of trying to predict the perfect moment to enter the market, determine whether a particular property at a particular price works for your situation and goals.
Sellers Should Study Their Competition
History matters for sellers, too.
During extremely competitive seller’s markets, homeowners may hear stories about houses receiving numerous offers within days. That can create expectations that remain long after market conditions have changed.
A home doesn’t sell in yesterday’s market.
It has to compete in today’s.
Sellers should look closely at comparable properties currently for sale, recent closed sales, properties that failed to sell and homes that required price reductions.
If similar houses are sitting for 60 days, expecting yours to sell in three because that happened several years ago may lead to disappointment.
Pricing, presentation, property condition, marketing and buyer demand can all affect the result.
A knowledgeable local real estate professional can be particularly useful here because they can help interpret what’s happening within a specific market rather than relying exclusively on national averages.
What About Renting?
Renting versus buying is another decision that frequently gets reduced to slogans.
“Renting is throwing money away.”
“You’d be crazy to buy with these rates.”
Neither statement tells you whether renting or buying makes sense for you.
Renting may provide flexibility and reduce certain responsibilities associated with homeownership. Buying may provide greater stability and the possibility of building equity over time, while also introducing expenses and risks renters don’t necessarily face.
Look at the numbers.
Compare rent with the realistic cost of ownership—not merely the mortgage payment.
Consider insurance, property taxes, maintenance, repairs, association fees, transaction costs and the amount of time you expect to remain in the property.
Then consider your life.
If you’re likely to relocate soon, your calculation may look very different from someone planning to stay in the same community for the next decade.
Do Your Own Research—Then Talk to People Who Know the Market
Real estate decisions are too important to base entirely on social-media predictions.
Research mortgage rates. Study recent sales. Look at inventory. Learn about the neighborhood. Understand the property’s history. Calculate different financial scenarios.
Then ask questions.
A good local real estate professional should be able to provide information about the specific area and property type you’re considering. Buyers may also benefit from speaking with mortgage professionals, insurance agents, inspectors, attorneys, tax professionals or other specialists depending on the transaction.
The objective isn’t to find someone who can predict the future.
It’s to gather enough information to make a better-informed decision.
Today’s Market Won’t Be Tomorrow’s Market
Perhaps that’s the biggest lesson real estate history provides.
There have been times when mortgage rates were substantially higher than many recent buyers were accustomed to. There have been periods of rapidly appreciating home prices and periods when prices declined. We’ve experienced housing shortages, construction booms, recessions, recoveries and dramatic shifts in buyer behavior.
Conditions changed.
And they’ll change again.
That doesn’t mean waiting is always the right decision. It doesn’t mean buying today is always the right decision either.
It means your decision should be based on more than fear about what might happen next.
Study the past. Understand today’s conditions. Narrow your research to the market that actually matters to you. Know what you’re trying to accomplish. Work with knowledgeable professionals when appropriate.
Then make your decision based on the information available and your own financial circumstances.
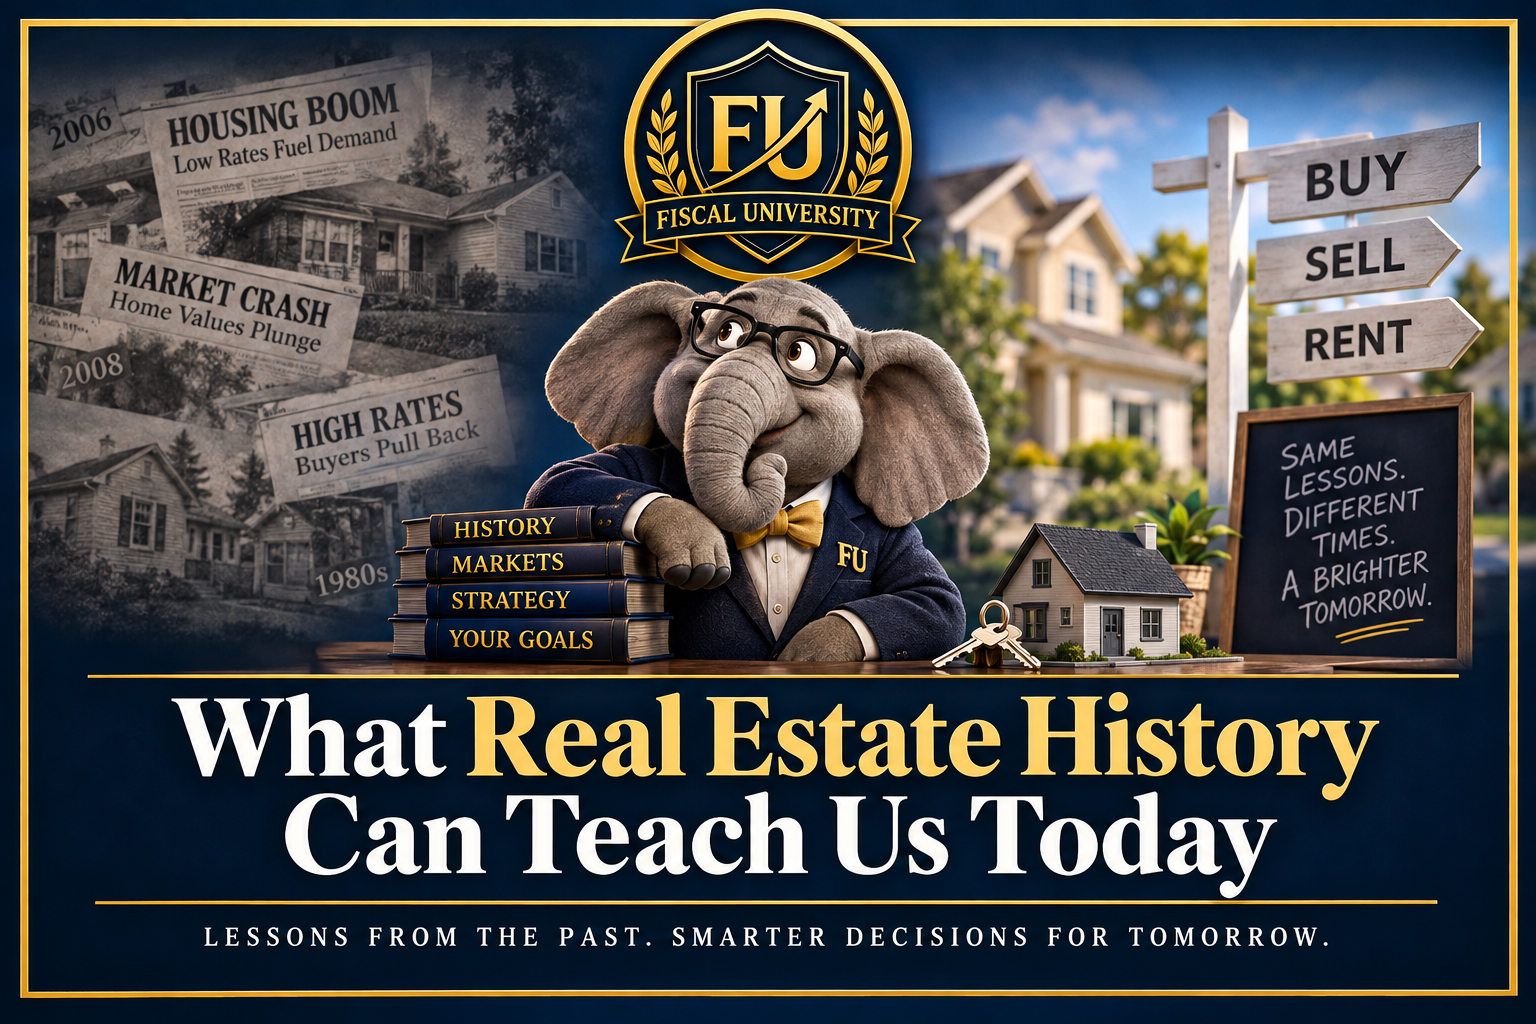
As Professor Elephant would say:
Learn from the past—but don’t assume it’s the future.
Fiscal University provides educational information for general informational and entertainment purposes only. We are not financial, investment, mortgage, tax, legal, or real estate professionals. Real estate markets, financing options, costs, laws, and individual circumstances vary. Conduct your own research and consult qualified professionals before making significant financial or real estate decisions.